About the author
Dedication
This writing is dedicated to the thirty million Americans who are being “screwed” (sorry, a slangy term, but none other seems appropriate) by the credit card companies. For those men and woman, and that of their families, I pray that this book will help stop their tyranny.
Contents
- 01Introduction
- 02Frank MacNamara
- 03Supreme Court Blunder
- 04Mafia Enforcers: Lawyers, Lobbyist & Credit Bureaus ?
- 05If it walks like a duck…
- 06Greed beyond limits
- 07Satan’s Credit Bureaus
- 08The “600” Prison
- 09“Cash or Credit?”
- 10Why do we pay more than others?
- 11Why does Washington allow this criminal activity?
- 12Some things are wrong – credit cards are worse
01
Introduction
Credit Cards, “The “Plastic Mafia,” are stealing money from 30 million Americans and are destroying the U.S. monetary system. They are charging disgusting, immoral, high interest rates which violate the electorate of all fifty states, who voted that 10 per cent should be the maximum legal limit. They deceitfully pretend to be good guys by creating Credit Bureaus to do their dirty work for them.
This book will introduce you to Frank MacNamara who cleverly invented the credit card (Diners Club) in 1950, explains how the Supreme Court decision of 1978 (Marquette v Omaha Service) gutted every state law regarding limits on credit card interest (“usury law”), and exposes how the credit card vultures have used their power (fueled by your money) to bribe Congress to make their crime against Americans “legal”. It is shocking to learn how the US Constitution Article I, regarding money, has been so obfuscated by the Plastic Mafia it would be easier to shake hands with Sasquatch than find an honest, accurate definition of money.
The “enforcers” of the Plastic Mafia are the Credit Bureaus who violate privacy laws by illegally collecting your information and ruining your financial reputation with information illegally given them from your credit card companies… no, they don’t break arms, just ruin your reputation instead.
Every AI I discussed this with agreed that historically credit cards were useful, but power and greed has intoxicated them to the point where they are threat not only to the United States, but also the world.
As I researched for this book, I talked with at least thirty Bank of America and Discover representatives. I am convinced that all disagreed with their employer’s policies, and agreed with my goal, that interest rates should be no more than 10 per cent.
02
Frank MacNamara
Diners Club was invented by Frank MacNamara in 1950 when he got a dozen or so New York restaurants to agree that people eating in their establishment could use a cardboard card to “charge” their meal to a central bank for payment. It started out very slowly and grew awkwardly, but due to the genius of one Matty Simmons, it evolved into the world’s currency. Like many inventions, today’s card is like comparing the “Monitor,” the world’s first submarine, to today’s nuclear attack submarines. Its promotional message from the outset was convenience, but greed has always been its motivation. So much so, that it has obliterated the usury laws of all fifty states. At an early meeting of Diners Club’s original management, Joe Titus argued, “It’s wrong. We’re giving a blank check to men and women who won’t be able to control their spending and will wind up in heavy debt and in court and eventually bankruptcy.” When someone said, everyone will carry a card someday, his response was, “I hope not, if they do this country will need to use the U.S. Army to collect the debt”.
There were early warnings from Wright Patman, chairman of the House Banking Committee, and Senator William Proxmire. Patman lamented that “Ever since the moneychangers were driven out of the temple of God, the banks have been trying to collect from both sides. Credit cards have finally made that possible.” Proxmire said, “unless we bring credit cards under control we are likely to produce a nation of credit drunks”.
03
Supreme Court Blunder
Marquette v Omaha Services, 1977 – the court decided that national banks could charge the same interest in all states what they charged in their “home” state. In effect, if your principal office was in Las Vegas, where gambling and prostitution was legal, you could offer them everywhere you did business – regardless of that state’s laws.
At that time all fifty of the United States had usury laws that averaged 10 percent. That’s what each state’s voters had mandated, and each legislature had enacted into a law. Usury laws prohibit “loan sharking”. Loan sharking is charging abusive interest on borrowed money. It has been declared unlawful in almost every country of the world since Jesus Christ condemned it has a “violation of God’s law”.
Lending Tree published that the average credit card interest in July 2026 was 23.79%. If thirty years ago all 50 states voted to limit it to 10 percent, declaring anything over that unlawful, how did the Plastic Mafia more than double it? Simple. They pay for it. Their lobbyists shower Congress with 100 million dollars a year.
Another sad truth is that the poorest without credit cards get cheated even worse: while credit cards users get a “5% rebate” and only pay $95 for their groceries, the poor without credit cards, pay $100.
That Supreme Court decision has resulted in Americans owing a trillion and a half million dollars of plastic debt in 2026. It caused this crisis by eliminating the 10 per cent interest limitation on credit. Once the Plastic Mafia took up residence in North Dakota and Delaware using the court’s “home rule” authority they eliminated any limit on interest rates nationally.
04
Mafia Enforcers: Lawyers, Lobbyist & Credit Bureaus ?
Around the turn of the century Bank of America executives and lawyers huddled in New York to discuss the legal minefield that credit cards might anticipate and what protection they had, or could create, to defend against any investigation that might challenge their legality…
Two of their biggest concerns, (1) usury laws, still on the books of most states, which prohibiting more than 10 per cent interest on credit and (2) the United States Constitution Article 1, section 5 that stated that the nation could have only one currency. The first, had a long history and the full support of the American people, and the second, though less well known, was the “law of the land”.
They agreed that they violated both laws… But, with time and money, they could rewrite them, and in case of the Constitution, they could rewrite the “definitions” of its words. They succeeded.
As stated beforehand, the Usury laws that protected Americans for two hundred years fell victim to the Supreme Court decision that allowed universal application of just one state’s law. Federal law also preempts state law, so it was easier to get that court decision by bribing Washington, DC than lobby 50 states to change each of their laws. Sadly, all 50 states had an average of 10 per cent as their legal maximum for loan interest, but like Redford and Newman in the Sting movie portrayed, the best criminals steal without the victim’s knowledge. That movie proved that the best crime is when nobody knows that they are being stolen from.
05
If it walks like a duck…
The only people who say credit cards are not money are the benefactors of the Plastic Mafia. Even the creator of credit cards, Frank MacNamara, called them “cash”. One of the best ways to know when a child (or a lawyer) is lying is when the first words out of their mouths are, “I didn’t do it”. (Oftentimes very loudly). We usually respond, “I didn’t say you did… ” and the argument is born.
The Plastic Mafia violates US Constitution (Article I) which says that there can only be one currency. Confronted by the possibility of litigation or the Supreme Court intervening, the Plastic Mafia has paid for a smorgasbord of “Legal Salads” which have rewritten the definitions.
When you ask for the definition of “credit cards” today, the first words from Federal Agencies and the Internet is literally screamed at you… “It’s NOT MONEY”! Funny, you asked what it was, but the first vehement answer is what it’s not. (“I didn’t rob the cookie jar.”)
The probability that someone is lying is enhanced by the “vehemence of their denial”. The quicker and louder the more that possibility exists. Knowing that credit cards are money and a violation of our Constitution, the Plastic Mafia has spent millions of dollars making sure that anywhere that question is asked the answer is “credit cards are not money”. And the more vehement they are, the more your intuitive consciousness should sound the alarm. I’ve asked a hundred people if credit cards are money, and the answer is unanimous, “are you kidding, certainly”?
“One hundred per cent cash is due, but when the Plastic Mafia offers you 5% cash back aren’t they saying, “one hundred per cent cash is due, but we are so generous, we’ll return 5 per cent of that cash as a discount”. The Plastic Mafia’s most common definition of money is “credit”, if so, then please get your accountant to tell mine, that the Plastic Mafia knows how to charge interest on credit. Absurd you say? Not if you have tons of other people’s money to alter the truth.
The Plastic Mafia advertises that credit cards are your friend. Oh yes, so are drugs, alcohol and assault rifles. When you have a temporary financial problem, they mug you for 25 per cent or make your life miserable, destroy your credit rating, and just maybe you even lose your job. If that smells fishy that’s why they are called loan sharks.
06
Greed beyond limits
The only thing the Plastic Mafia hasn’t stolen is first base… they use every computational trick to squeeze your last dollar out of you. If you don’t pay the full amount due, you will be charged interest on all of it, not just the remaining balance. They charge interest starting the first day you buy (interesting note, when you make a deposit they won’t allow you to use any of it for days, while at the same time they immediately start charging you interest when you buy something with their plastic). They lie about airline “miles” (they don’t even use actual miles anymore). They charge you interest and as well as “bully” the companies that use them to pay a 2 to 4 per cent “swipe charge”. They promote “Recurring charges” which are infuriating, if not illegal. Maybe you subscribed to Disney last year, but since then you haven’t watched their channel or decided you didn’t want it anymore. Good luck trying to cancel. Just try to find the “unsubscribe” button or more likely, due to human nature, you won’t be aggressive because, “it’s only $9.58 a month”, or procrastinate “I’ll cancel it later”…
07
Satan’s Credit Bureaus
The so called “credit” bureaus are “owned” by the Plastic Mafia and will mail you a free, (if you want every loan company in hell to mail you their loan program) twenty pages of details that even your accountant cannot translate). Your Plastic Mafia will slyly recommend that you get in touch with the credit bureaus “free” to “check on your status”. Oh, they are so kind to do that, but guess what?… In the next few weeks because your name was “sold” to hundreds of loan companies, you will receive dozens of unsolicited letters boldly announcing that you are PRE – APPROVED for a loan up to $100,000! “Holy Ego Trip! I must be rich”. And millions of people a little in debt, expand it to even more.
08
The “600” Prison
If your “FICO score” gets below 600 you may never own a house or a car. Be tardy on a just a few payments and Satan’s “credit bureaus” have the power to destroy you. It’s part of the scam. The Credit Card companies want you to believe that they are wonderful friends, so they support these three “non-for-profit” credit bureaus to do their dirty work. Don’t be charmed into believing that they are not the Plastic Mafia’s “ENFORCERS” And good luck trying to fix any of their mistakes or you’ll learn what it used to be like to be a fish on Friday in a Catholic’s house. (It’s amazing what money can buy if you want to sound like the good guy… Credit “Bureau” – doesn’t that sound sweet? “Not for profit” – they must be sweet. “Credit Score” – sweeter yet… I must have hit a home run.)
If they were honest, their names would be “Debtors Purgatory” or “Hell’s Debt Collectors.” But they protect you from “identity theft” and unleash your “financial power”. If you believe that – well, it’s hard to see through wool.
09
“Cash or Credit?”
Let’s face it. Credit cards can be intoxicating. Who doesn’t want to buy their children nicer toys, or to go for dinner to celebrate an accomplishment, or give the church money to help the homeless.
Most of us know better and will survive an occasional spending spree. But what happens far too often is a major unexpected expense comes along that ruins our plans.
Your employer discontinues overtime. Your car needs new tires. Your brother-in-law doesn’t pay you that money he borrowed. Your child needs glasses. Worse, there’s a family medical crisis and regardless of what you thought, your insurance doesn’t cover the bill. Life is full of ups and downs, but far too often there seems to be a financial challenge at just the wrong time… and don’t think for a moment that the Plastic Mafia doesn’t care…. your emergencies make them richer.
Hell should offer the credit card companies front row seating…
10
Why do we pay more than others?
The poor, minorities and those just starting out are being raped because they cannot qualify to use credit card money – only dollars. So tragically, fifty million Americans pay $100 for groceries while those using credit cards pay only $95. And, if you add the credit card cost that the retailer includes in his price as a cost of doing business, the total is an outrageous 10 per cent. In effect, the plastic Mafia steals at least $1,500.00 a year from those least able to afford it. That is so illegal. So immoral. So unconstitutional. So unfair. It is a class action lawsuit begging to be uncaged.
One of the strangest side effects of poor people not qualifying for credit cards is increasing theft rates in poor neighborhoods. Because they don’t qualify to have credit cards they keep cash on hand which attracts local ne’er do wells to break into their homes to steal it.
11
Why does Washington allow this criminal activity?
The answer is so obvious that even that dumb rock can answer it. The Plastic Mafia owns Congress hook, line and page boy. The credit card companies admit to spending 100 million dollars a year lobbying congress and they still can report their profits at 50 per cent. (The average profit of United States’ companies is 7 per cent). If you use your credit card to send money to your favorite politician, the plastic Mafia can pocket as much as 30 per cent of it. Our Constitution states that there will be only one “money”. If that is true, credit cards are unconstitutional and should be banned.
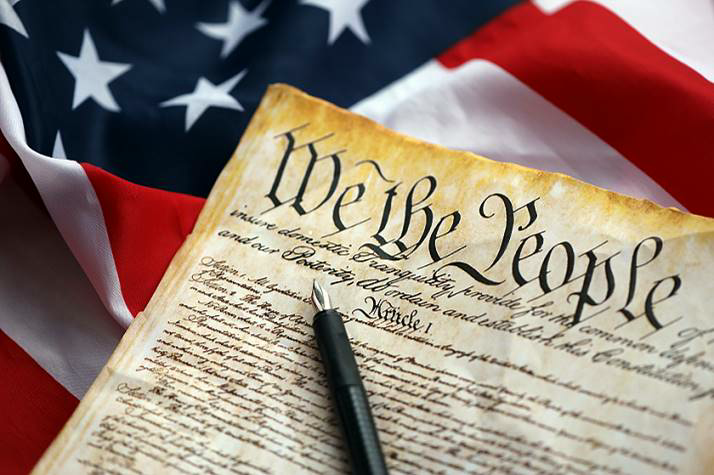
Article I, US Constitution stipulates
“only one money.”
So, what are credit cards? Holy legal salad. If you want the best proof that the plastic Mafia knows they are immoral, read how they have spent millions of dollars altering the Federal Reserve and other government entities, as well as many “on the payroll” law firms, to “redefine” credit cards as not money: “they are extended loans”, “promises to pay,” “not a final method of payment,” “a deferred transaction,” “the issuer pays the merchant on your behalf”… and my favorite salad dressing of all, “they do not store value”. (What the heck does that mean?)
The words “legal tender” is still displayed on U.S. paper money and originally, words to the effect that this piece of paper promised silver or gold (the latter before Nixon) from a national bank. And that is exactly true and the ultimate argument that credit card companies lie about but want you to think otherwise.
Social Security decided mid-2026 that it will no longer mail checks, instead payments will go to a bank electronically. I wonder how much influence the Plastic Mafia’s money has had to this destruction of cash? (That’s 70 million people who are forced to use banks and not cash). It’s ironic that the Washington bureaucracy is so complicit in eliminating cash, contrary to constitutional law.
Poor people are being cheated because they cannot use Satan’s money to purchase at a discount and more than half of American’s using Satan’s money are cheated because they pay almost thirty per cent interest to the plastic Mafia every month.
But everyone suffers, because if credit cards didn’t exist, the cost of living in the United States would decrease by 5 to 10 percent. Dante’s third circle of hell promised that “those who perverted human intellect to fraud their fellowmen would be punished in a realm of icy mud”. (I realize that circle 7 and 8 deal with theft and dishonestly, but I chose circle 3 for illustration because the Plastic Mafia is so absolutely, unashamedly greedy).
Don’t forget that the Plastic Mafia makes an outrageous 50 per cent profit on credit cards whereas the average United States company earns only 7 per cent. (Bank of America brags that it made 48 per cent from its plastic last year.)
I hope that the children and grandchildren of Brian Moynihan, CEO of Bank of America, and all fellow bank CEO’s, included the one who named his yacht, “Overdraft”… read this and ponder where their standard of living came from…. And, before condemning me and what I am fighting for, please remember that seventy years ago it was illegal to charge more than 10 per cent interest on any loan in each of our fifty states.
12
Some things are wrong –
credit cards are worse
It is despicable that The Plastic Mafia’s wordsmiths not only cleverly change word definitions that might be damaging to them, but also spend millions of dollars brilliantly suggesting that those 30 million Americans who are paying loan shark interest are bad people because they cannot control their spending. That propaganda is so profound that those thirty million people are embarrassed to speak out. What is bad, in fact inhuman, is to charge nearly 30 per cent interest on those who desire to live a little better. “It’s your fault” is inappropriate to tell those who add a little too much sugar occasionally. The shame, OUTRAGE, is caused by those who charge ghastly interest, not people who overspend. They are embarrassed and too intimidated to complain. If deception was a star, the Plastic Mafia would be a whole galaxy.
The “plastic Mafia” is evil. It damages tens of millions of lives, adds five per cent to inflation, ignores usury laws and violates the United States Constitution.
10 per cent interest should be the maximum!